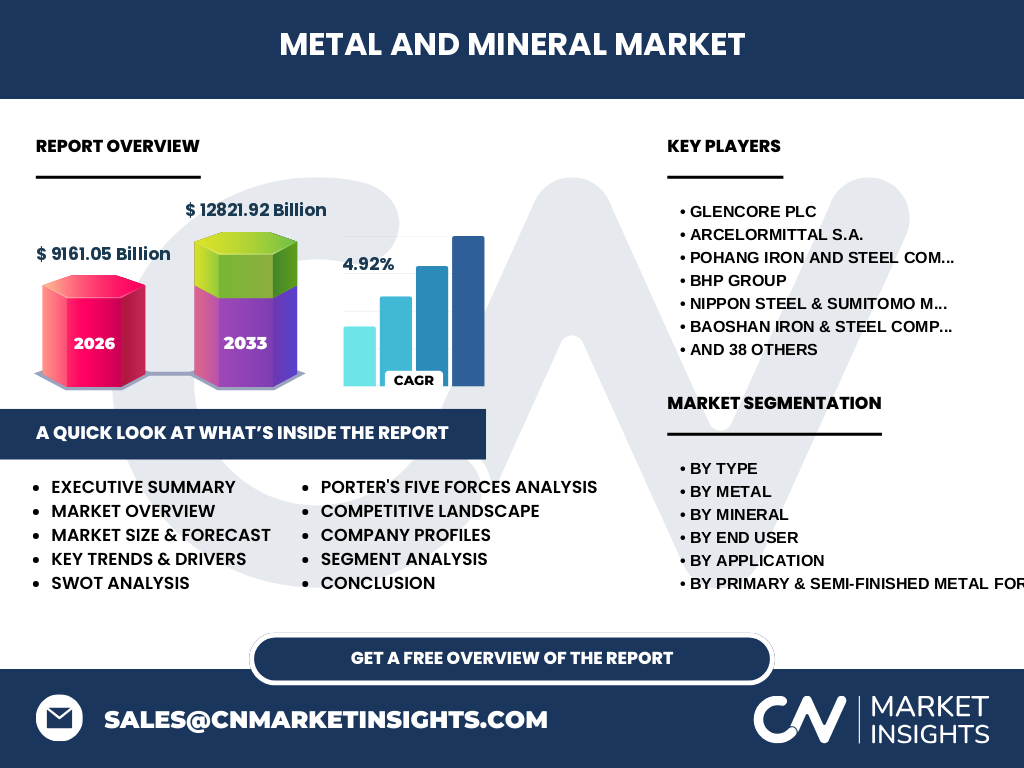
Market overview of the global Metal And Mineral Market
The Metal And Mineral Market serves as the foundational bedrock for global industrialization, encompassing the extraction and processing of raw materials. With a 2026 valuation of 9161.05 Billion, this sector facilitates everything from infrastructure development to high-tech electronics. Our research identifies this market as a critical barometer for global economic health, spanning from upstream mining operations to the refined metal output essential for modern supply chains.
Structural Growth Drivers and Market Constraints
Growth is primarily propelled by the energy transition, which demands massive quantities of copper, lithium, and rare earth elements. While industrialization in emerging economies bolsters demand, the market faces significant logistical hurdles and stringent ESG regulations imposed by bodies like the International Council on Mining and Metals (ICMM). These factors force players like Glencore plc and Rio Tinto to optimize extraction efficiencies to maintain their competitive edge.
Emerging Trends in the Metal And Mineral Market
The shift toward decarbonized extraction is the most significant trend. We observe mining giants prioritizing green steel and circular economy initiatives. Furthermore, digitalization of mine sites—utilizing AI for predictive maintenance—is becoming the industry standard. Companies like BHP Group and Vale S.A. are actively reconfiguring their operational portfolios to leverage these high-efficiency, lower-carbon mineral and metal processing technologies.
COVID-19 impact and the road to recovery
The pandemic caused a disruptive supply chain contraction, initially stalling construction and manufacturing output. However, the post-2020 recovery saw a aggressive rebound fueled by infrastructure stimulus packages. The trajectory shifted toward building resilient, localized supply chains, as companies moved away from sole-source dependency, ensuring that primary metal forms remained accessible despite ongoing global volatility in maritime freight and energy costs.
Competitive Benchmarking and Market Concentration
The Metal And Mineral Market exhibits a high degree of concentration among top-tier producers like ArcelorMittal S.A., Nippon Steel, and Freeport-McMoRan Inc.. Strategic dynamics are defined by vertical integration, where leaders control the path from metal ores to refined products. This consolidation allows majors to exert influence over global pricing, creating significant barriers to entry for smaller, fragmented players in the exploration and extraction niches.
Executive Summary of Global Market Performance
The global Metal And Mineral Market is set for robust expansion, reaching a projected 12821.92 Billion by 2033 from a 2026 base. Growing at a CAGR of 4.92%, the sector is entering a period of structural transformation. Key takeaway: investors should focus on companies positioned for the energy transition, as demand for non-ferrous and precious minerals consistently outpaces conventional industrial materials in the long term.
Market Forecast for 2027-2033
Based on our proprietary analysis, the market will maintain a steady 4.92% CAGR throughout the forecast period. We anticipate a total valuation of 12821.92 Billion by 2033. This growth is underpinned by massive capital expenditure in electrical grid infrastructure and a sustained demand for refined and crude metals needed for global urbanization, particularly across the Asia-Pacific and Latin American industrial hubs.
Segmentation Analysis: Categorizing Value Streams
The market is segmented into three primary domains: Minerals, Metals, and Primary/Semi-Finished Forms. Our research highlights that non-ferrous metals are currently outperforming due to their role in electronics. By end-user, Energy & Utilities has emerged as a high-growth segment, reflecting the urgent global requirement for base minerals needed for renewable energy infrastructure and long-term grid electrification projects globally.
Regional Market Performance and Distribution
Regional dominance remains centered in resource-rich nations. Asia-Pacific remains the largest consumer, driven by manufacturing demand in China and India. Meanwhile, Latin America—with companies like Southern Copper Corporation—serves as the critical upstream provider. Our research confirms that localized logistical hurdles in regions like Africa are currently being addressed through massive infrastructure investment, effectively balancing regional supply with the ever-increasing global demand for precious and industrial minerals.
In-depth regional review of key markets
North American markets emphasize technological innovation in mining, while Europe focuses on sustainability compliance under EU Green Deal frameworks. China remains the epicenter of both production and consumption. We observe that firms like Baoshan Iron & Steel are heavily integrated into the construction sector, whereas North American firms emphasize precious metals exploration, tailoring their production to the high-value needs of the aerospace and defense manufacturing industries.
Company Profiles and Strategic Positioning
Industry leaders maintain varied strategic postures. Glencore plc specializes in commodity trading and diversified mining, while Newmont Corporation and Barrick Gold Corporation focus on precious metals portfolio optimization. Others like Alcoa Corporation prioritize aluminum-based sustainability. Each player is aggressively aligning with decarbonization mandates to satisfy institutional investors, ensuring their operations withstand the intensifying scrutiny from global environmental and governance bodies regarding mining impacts.
Porter's Five Forces analysis for the sector
The Metal And Mineral Market faces intense competitive rivalry due to the presence of large-scale, well-capitalized entities. Threat of substitution is low for essential minerals but high for secondary alloys. Buyer power is moderated by the critical need for supply security, while the bargaining power of suppliers is high, as access to high-grade mineral reserves remains a finite, geographically restricted, and highly competitive strategic asset.
SWOT Analysis: Strategic Outlook
Strengths: Established global supply chains and massive production capacities. Weaknesses: High energy-intensity and environmental footprint. Opportunities: Rapidly expanding green energy markets and technological advancements in mineral recovery. Threats: Geopolitical instability impacting resource-rich regions and unpredictable regulatory shifts. The data suggests that companies effectively managing these risks will secure long-term market dominance, while laggards face significant operational disruption and potential divestment from key stakeholders.
Value chain analysis from extraction to end-use
The value chain originates at the mine site, moving through beneficiation into refined and crude metal forms. Value is added during the metallurgy stage, where processing plants convert raw ores into high-purity inputs for chemicals manufacturing or glass products. Efficiency at each junction is critical; firms that control the logistics from extraction to refinery enjoy the highest margins, successfully insulating themselves from volatility in global raw commodity prices.
Investment Insights and Strategic Recommendations
We recommend focusing capital on energy minerals (lithium, cobalt, copper) given the 4.92% CAGR trend. High-potential areas include automated mining and recycling technologies, which mitigate regulatory risk. Investors should favor firms with strong ESG credentials, such as Anglo American Platinum or Teck Resources Limited, as they are best positioned to navigate the tightening regulatory landscape while capturing long-term value from the ongoing global energy transition.
Conclusion and Key Takeaways
The Metal And Mineral Market is entering a vital phase of growth, reaching 12821.92 Billion by 2033. The primary transition is from high-volume traditional output to high-value strategic minerals required for the green economy. Success in this sector requires a balance between operational scale and sustainable practice. Firms that master the digital-physical bridge will outperform, securing their role in the global industrial architecture of the next decade.
Research methodology and data triangulation
Our methodology utilizes triangulated research combining primary data from stakeholder interviews with executives at major players, such as Vedanta Limited and First Quantum Minerals. This is validated against trade registry data, public financial filings, and macroeconomic indicators. We utilize a bottom-up estimation model to ensure the precision of our 9161.05 Billion baseline, cross-referencing regional supply indices with local manufacturing consumption patterns for maximum accuracy.
Scope of the report: Parameters and Limitations
This research covers the Metal And Mineral Market globally, specifically focusing on ferrous, non-ferrous, and precious segments across construction, manufacturing, and energy sectors. The scope includes upstream mining, midstream refining, and primary manufacturing. While comprehensive, this analysis excludes niche micro-alloy variants and specific proprietary laboratory-grade chemicals, focusing instead on high-impact commodities that influence the broader global economic landscape and infrastructure investment trends.
Recent developments and strategic moves in the industry
The industry has seen aggressive M&A activity and partnership formation, such as Lundin Mining Corporation's expansion efforts and Glencore plc's focus on battery metals. Recent announcements highlight a commitment to carbon neutrality by 2040 across major players. These strategic pivots, combined with technological launches in automated drilling and AI-driven mineral exploration, indicate a market-wide trend toward efficiency-first production, essential for sustaining the growth trajectory through 2033.